


Private markets can broaden the opportunity set for charities foundations and endowments while offering greater scope for impact and influence. But investors need to overcome challenges around governance, liquidity, costs and implementation to capture those benefits.
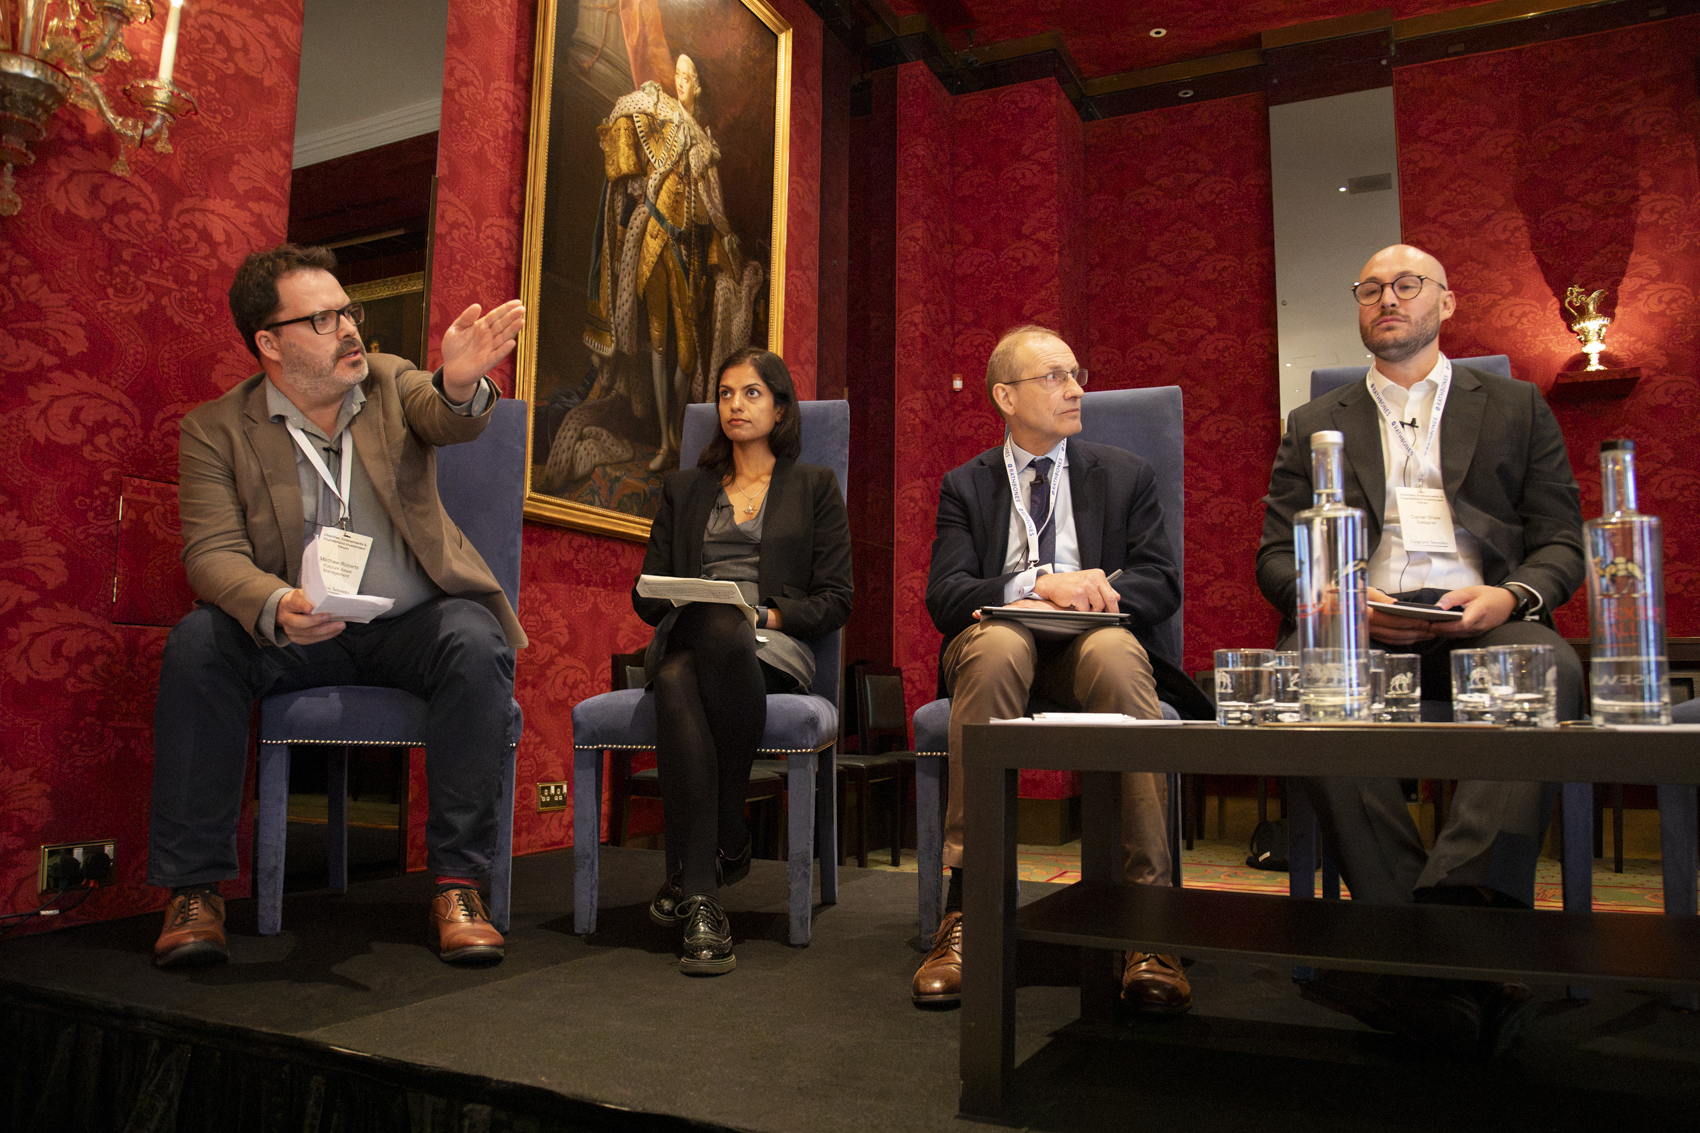
Charities, endowments and foundations (CEF) have good reasons to consider private markets – but making them work requires careful attention to costs, liquidity, governance and mission alignment. That was the message from a panel at Longview Networks’ forum for the sector last week, which brought together asset owners, investment managers and advisers at different stages of the private markets journey.
David Ballance, chair of the investment group at Christ Church, Oxford, said the growing ability of companies to remain private for longer strengthened the case for investors to look beyond listed markets.
“Given the amount of capital available in the system at the moment, companies can stay private for longer, and therefore they may be out of reach if an endowment or foundation’s policy strategy is limiting itself to publicly quoted vehicles,” he said.
For Matthew Roberts, partner at Fulcrum Asset Management, diversification is only part of the attraction. Private ownership can also give investors greater influence over companies, while providing capital to parts of the financial system that ultimately feed public markets.
“You have more control. You have more influence over the businesses,” he said. “And then the third one is you’re contributing to the vitality of the financial system. If you don’t have a healthy venture capital market, you don’t have a healthy listing market.”
However, the panel spent much of its discussion examining the conditions that need to be met for those advantages to translate into successful investments.
Daniel Shaw, head of endowments and foundations at Gallagher, said investors first needed to establish whether they were being adequately rewarded for the additional risks.
“They are illiquid, and so that reduces your flexibility to change your mind down the line,” he said. “There’s complexity and there’s governance burdens, so you need to have the requisite time, governance resources and expertise to consider what to do.”
Fees provided another hurdle, while higher interest rates have changed the environment for managers that had previously benefited from cheap leverage. Shaw said this increased the importance of identifying managers with demonstrated ability to improve the operations of portfolio companies or assets.
For the John Ellerman Foundation, entering private markets has required considerably more preparation than initially anticipated. The £150m foundation has allocated its social investment portfolio – around 10% of the value of its endowment – entirely to private markets.
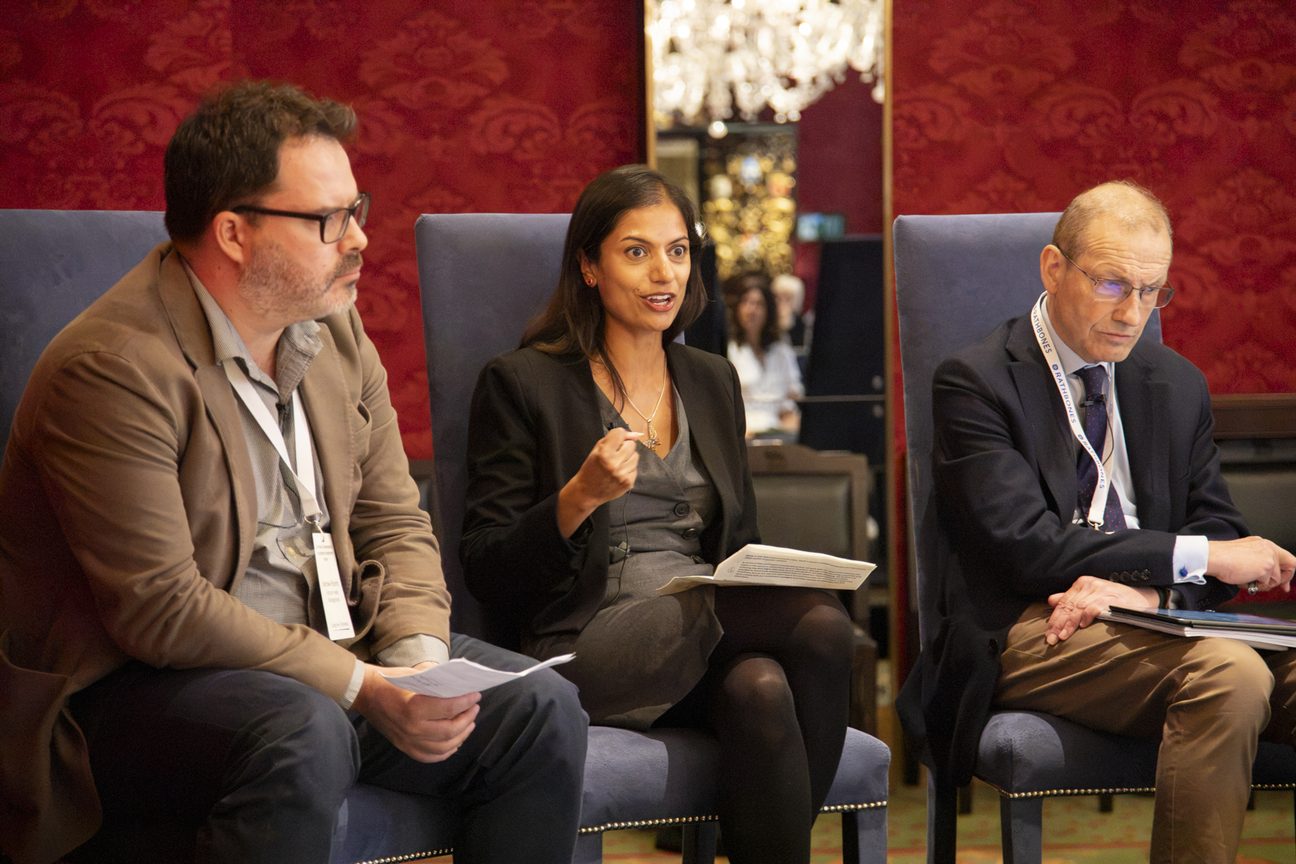
Sufina Ahmad, director of the foundation, said its motivation was primarily the potential to increase the impact achieved through its investments, alongside the financial returns needed to sustain its grant-making.
But moving from responsible investment into social investment required new policies, terminology, internal understanding and investment advice.
“We underestimated the amount of building blocks we would need to establish to get going,” Ahmad said. “One or two years on, we’re starting to get some traction. But it still feels like it took a lot longer than we anticipated.”
Hidden risks
Private assets also need to be considered in the context of the wider portfolio. Ballance cautioned against assuming that apparently smoother valuations necessarily provide genuine diversification from listed equities.
“Private equity, and in fact lots of things in private markets, can look less volatile because they don’t price,” he said. “Everything looks quite stable if it only has three-monthly pricing.”
Liquidity assumptions also require stress testing. With IPO activity subdued and cash returning more slowly than investors had become accustomed to, Ballance advocated using “pretty unheroic and conservative assumptions” when modelling commitments, investments and distributions.
Institutional investment Conferences & Summits from Longview Networks
Costs can similarly extend beyond headline management fees. Roberts highlighted cost transparency, cash drag and the interaction of carried interest across a portfolio of managers as areas requiring particularly close scrutiny.
“Watch out for cash drag when it comes to building private market portfolios,” he said. “It can cost you 3% per annum if you don’t manage this properly.”
He also warned that an investor could select seven successful managers in a portfolio of ten and still find that multiple layers of carried interest materially reduced overall returns. “Forensic due diligence on those can save you a lot of money,” he added.
Mission matters
For CEF organisations, financial and operational considerations sit alongside another requirement: ensuring long-term investments remain aligned with the organisation’s purpose.
Shaw said the breadth of private markets made intentional manager selection particularly important. “You can deploy in private markets in so many different ways, so being really intentional and focused about the parts of the markets and the types of managers and the DNA of the organisation that you’re partnering [with is important],” he said.
“These are potentially long-term partnerships that you’re making, and so you need to be absolutely sure that partnership is going to be in alignment with what you’re trying to deliver overall in your purpose as an organisation.”

Ahmad said private markets presented transparency and reputational questions for her foundation, but also offered opportunities to extend the impact of its grant-making. Its first two social investments have focused on housing and responsible consumerism.
“The opportunity that entering into private markets provides us means that we can only be adding to the impact of our grant-making,” she said.
Shaw similarly pointed to the potential for primary capital to contribute to areas including healthcare, climate and supply chains, as well as real assets supporting the green transition.
“The additionality that private markets can provide in this space is one of the main reasons to make this a worthwhile endeavour,” he said.
For Ballance, that opportunity ultimately justified the additional work involved – provided investors recognised what they were taking on.
“There may be more spade work – due diligence, governance – by the foundation itself,” he said, so investors should expect an appropriate return premium for accepting both illiquidity and the additional burden of investing privately.