
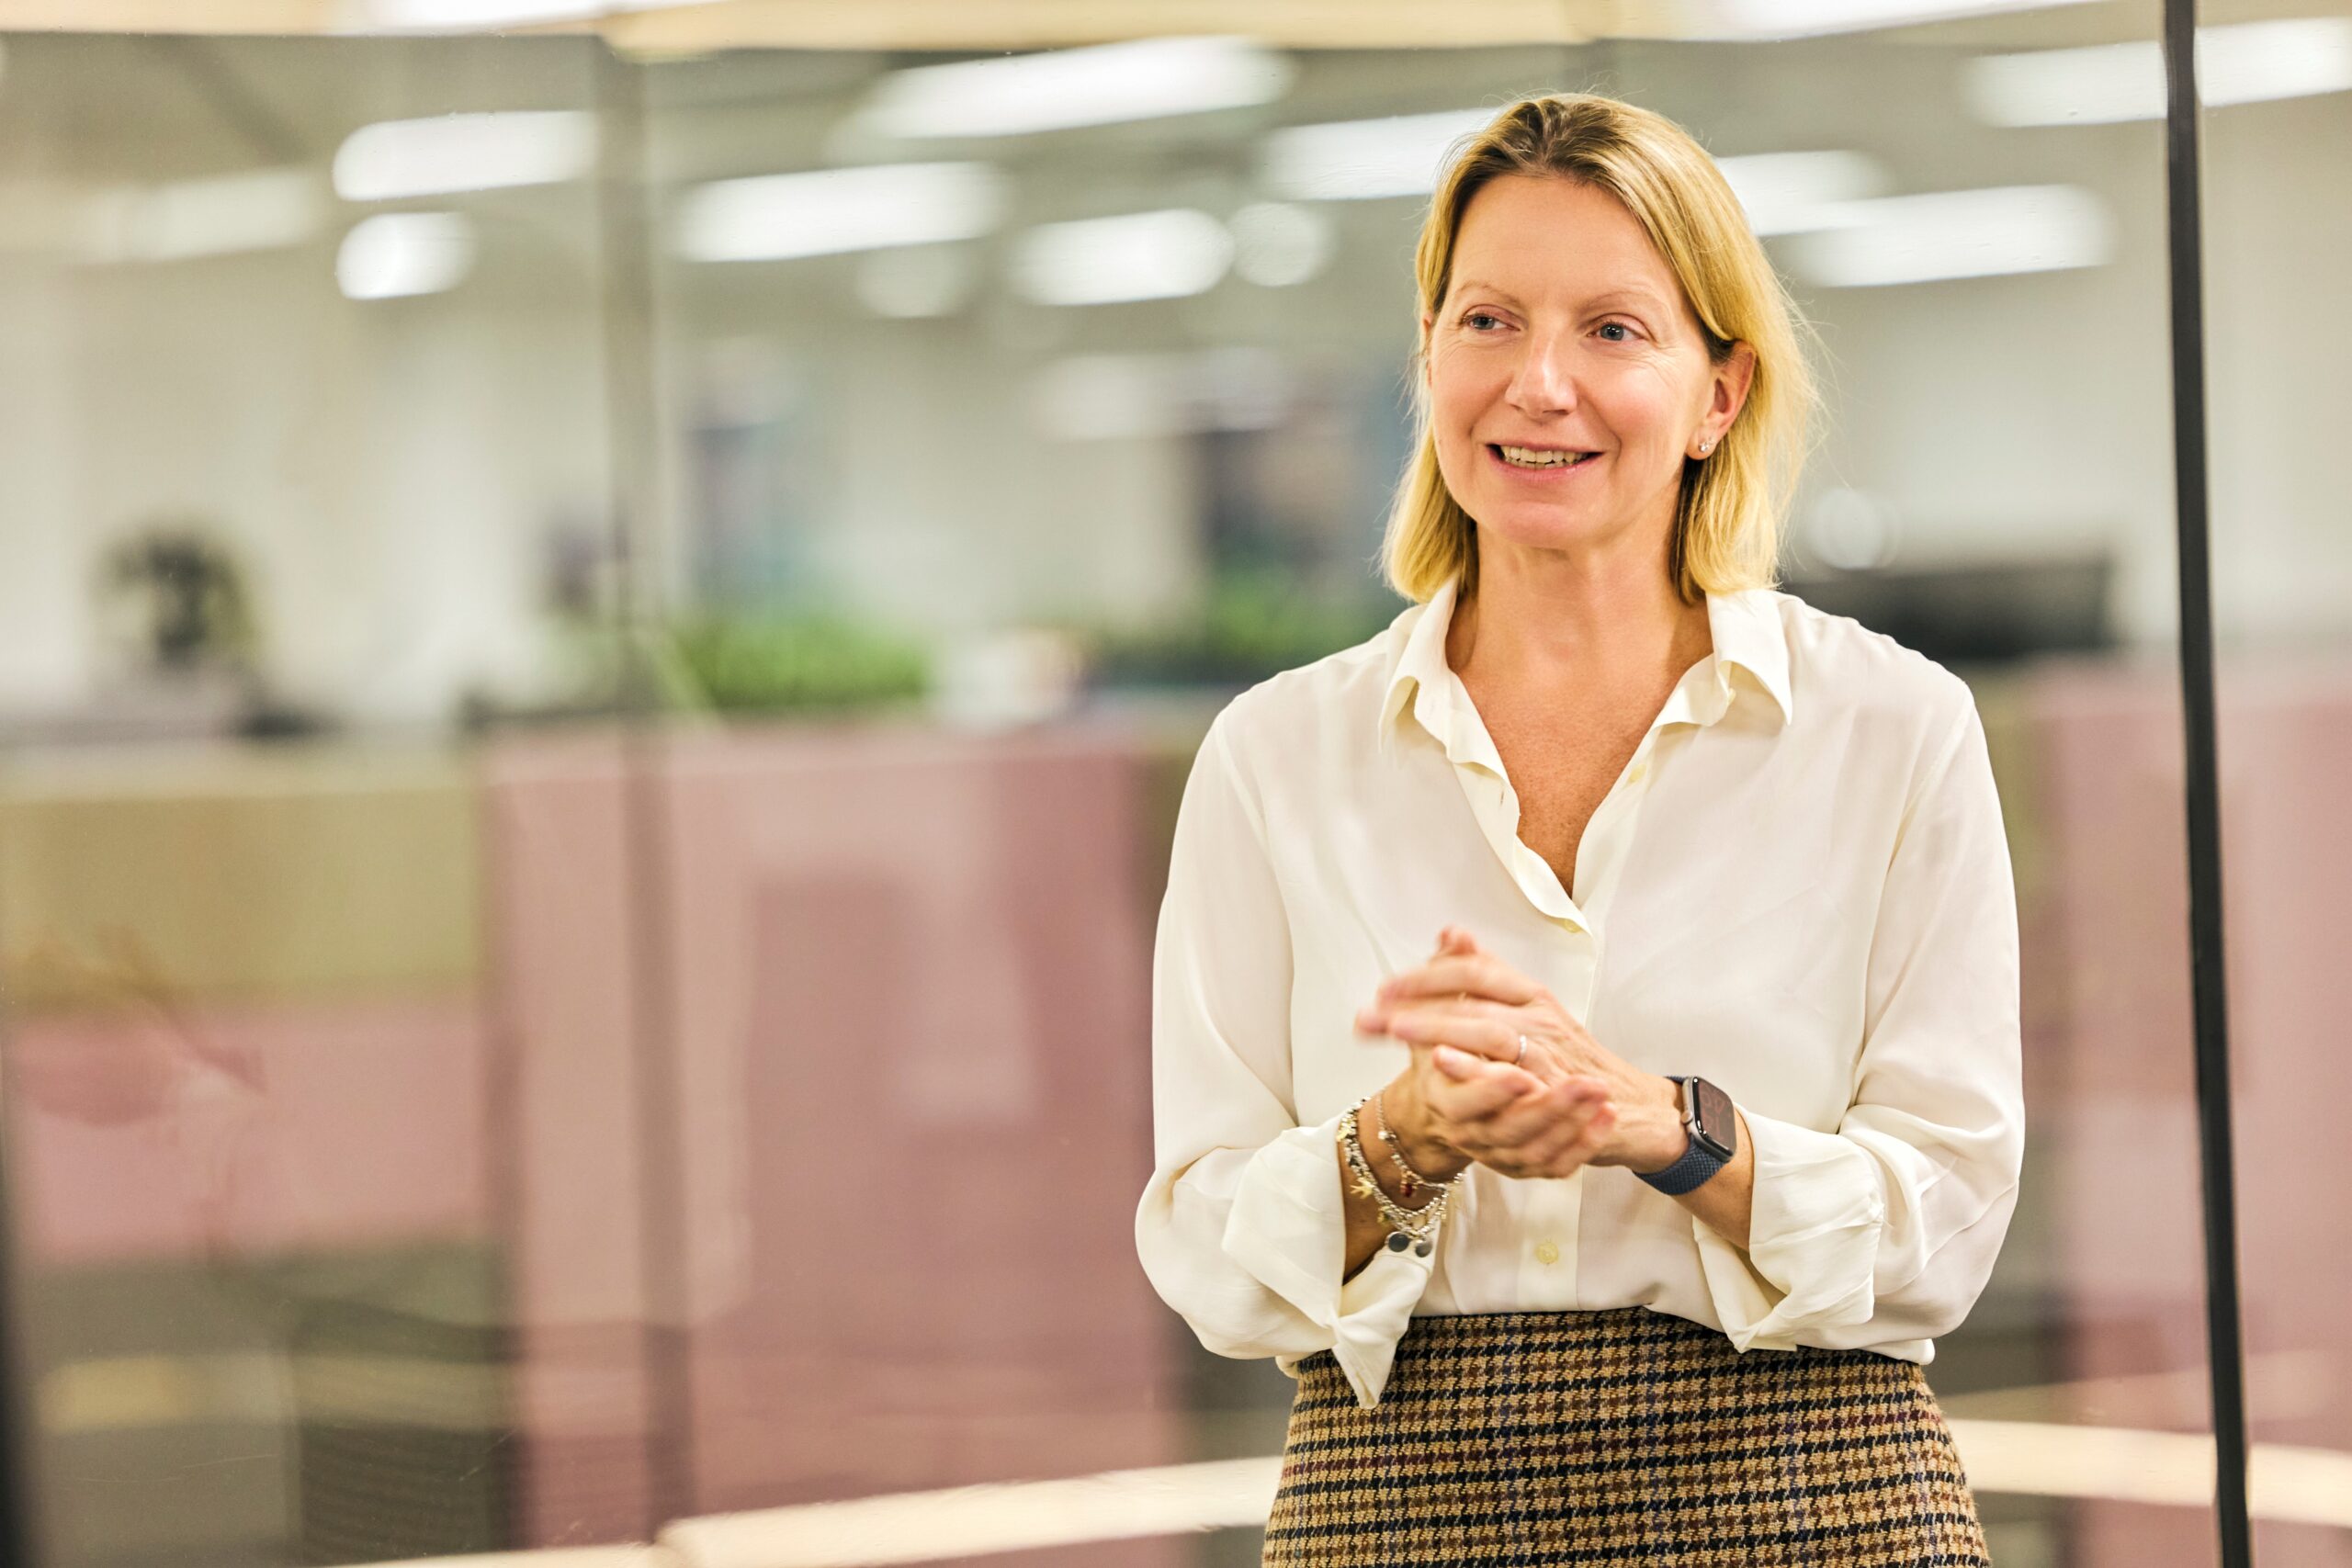

As insurers explore new opportunities across structured credit and AI infrastructure, Standard Life’s Michela Bariletti argues that understanding underlying risks and maintaining underwriting discipline are essential to finding value.
When one of the UK’s largest insurers finds itself holding more government bonds than expected, it says something about the challenges involved in finding relative value across public and private credit markets.
Standard Life has maintained an overweight position in gilts for the past two years as tight credit spreads have made it increasingly difficult to justify taking additional risk.

Michela Bariletti, the group’s chief credit officer and head of global investment research, says: “We see more value in keeping the option of capturing wider spreads in the future than crystallising current spread levels – particularly in the current CapEx super cycle, which is likely to keep bringing attractive investment opportunities on both the public and private sides.”
The group manages approximately £300bn in assets, including around £45bn on its balance sheet backing defined benefit pension obligations.
Bariletti’s priority is to identify opportunities that justify the additional risks. She believes opportunities remain for insurers prepared to look beyond conventional lending markets. “As relative value investors, we are looking for risk-adjusted returns that help us manage our balance sheet.”
Private markets remain an important part of the investment strategy, offering diversification, access to a wider range of borrowers and the potential to match long-term liabilities. “We continue to see private markets as a good differentiator and potentially where we can find some value,” she adds.
Finding value
Bariletti believes that investors with the necessary expertise can differentiate themselves by originating and negotiating transactions directly.
“If you have a highly syndicated loan, such as a US private placement, where it’s distributed widely and easy for everyone to compete, then you probably have less of a pickup,” she explains.
“We find value by conducting bilateral negotiations. We work directly with borrowers, rather than going after more widely syndicated loans.”
Longview Networks’ Insurance Investment Forum | London | 20 January 2027
This requires investment in internal capabilities, particularly the ability to analyse complex structures and negotiate protections. Standard Life negotiates covenants, repayment structures and downside protections to improve the resilience of individual investments.
Public markets remain essential for liquidity, while private markets provide access to a wider range of borrowers and longer-dated assets.
“We always compare the premium we can get in private markets to a comparable basket of public assets – we want to be compensated for the additional risk,” Bariletti says.
“While we could potentially exit assets in the secondary market, a private strategy is not comparable to a public bond strategy.”
Bariletti notes that tightening spreads in public markets eventually feed through into private transactions, although the latter typically take longer to adjust. “Whether private or public, credit is credit,” she says.
Expanding opportunities
Bariletti notes the Solvency UK reforms, including the introduction of highly predictable cash flows, have provided additional flexibility for insurers seeking to incorporate structured finance into matching adjustment portfolios.
Historically, many structured credit investments have been difficult to accommodate because their cash flows can be floating-rate, shorter-dated or subject to variable repayment schedules.
One area attracting greater attention is structured credit, particularly portfolio lending arrangements backed by pools of underlying assets.
The regulatory changes are encouraging insurers and investment managers to explore structures capable of meeting these requirements.
“There’s been a surge of flavours within structured credit. You can go from traditional CLO-type structures to more fund finance-type solutions,” she says. “The structure may differ slightly, but the concept is ultimately leveraging a pool of assets.”
Such arrangements can provide exposure to a wider range of borrowers and underlying assets, potentially through structures designed to meet insurers’ matching adjustment requirements.
Institutional investment Conferences & Summits from Longview Networks
However, the benefits will differ for each insurer, depending on its internal model, approved MA applications and investment capabilities.
“What might be efficient for us may not be efficient for another insurer, depending on how they are modelling it and their MA application,” Bariletti explains. “The rules are the same for us all, it’s how you implement the rules internally that may differ.”
Standard Life has been examining opportunities across collateralised loan obligations and financing provided to investment funds, including structures backed by credit and private equity assets.
Yet the growing sophistication of these investments makes understanding the underlying collateral a key consideration.
Underwriting discipline
For Bariletti, the principal danger is mistaking structural sophistication for genuine diversification. “You don’t want to be fooled into confusing complexity and diversification – you need to really understand the underlying risks,” she says. “You need to be able to unfold the structure and understand the driver of your investment.”
That requires detailed analysis of the collateral, the borrowers ultimately responsible for repayment and the asset managers or sponsors supporting a transaction.
Investors must also understand what happens when an investment performs poorly, particularly where illiquidity makes an early exit difficult.
“Private investments are illiquid, so you are along for the ride. Therefore, you need to be comfortable about how, if things go wrong, you would get your money back. No structure will compensate you enough to turn a bad credit into a good credit.”
These considerations are becoming especially important as insurers assess opportunities arising from the rapid expansion of artificial intelligence.
Financing AI
The scale of investment required to develop AI infrastructure creates substantial opportunities for long-term lenders. However, uncertainty surrounding technological development, valuations and obsolescence complicates the underwriting process.
“We are cautiously looking at data centres,” Bariletti says. “It’s not that we don’t have appetite for them, but you’ve got to be very careful in terms of the valuation, technology risk and obsolescence risk.”
Bariletti says the sector presents new considerations, such as whether investors have better protection when they finance individual data centres or lend directly to the hyperscaler.
“Is it better to underwrite a data centre with a long lease to a hyperscaler – or lend to the hyperscaler itself? Which channel gives you more protection to the potential obsolescence risk?”
Lending to a hyperscaler may reduce the downside from an individual data centre becoming obsolete; financing assets directly can offer higher returns in exchange for construction, infrastructure and other risks.
Both approaches provide exposure to the expansion of AI, but they leave lenders bearing different combinations of corporate credit, construction and technological obsolescence risk.
“Are you paid enough for the risk you’re taking?” she asks. “We’re doing quite a deep dive to understand all the various parts of the system and trying to understand where we want to play.”
There are also opportunities beyond data centres themselves. “The flip side of AI is the opportunity to finance the ecosystem. Data centres need power, water and transmission grid capacity.”
These supporting assets may offer more familiar risks and cash-flow characteristics for investment-grade-focused insurers.
Bariletti says Standard Life already invests in areas such as energy, the energy transition and power infrastructure, which can provide relatively predictable cash flows.
Nevertheless, questions remain about whether the enormous expenditure planned by technology companies will generate sufficient returns. “Are they going to be able to get the return on their capex? I don’t think anyone has the complete answer,” she says.
While the hyperscalers currently benefit from strong balance sheets and high credit ratings, the returns generated by their AI investments are becoming increasingly material to their bottom line.
Persistent uncertainty
The wider economic environment reinforces the need for selectivity. Bariletti expects volatility to remain a feature of investment markets, alongside interest rates that settle at higher levels than those prevailing during the prolonged low-rate period following the financial crisis.
“Volatility is here to stay. I don’t think this period is going to come and go. It’s something that we need to learn to manage and live with.”
However, volatility can also create opportunities, allowing investors to obtain greater compensation for risks that may have been inadequately priced only days earlier. For insurers, that makes retaining the flexibility to deploy capital when valuations become more attractive particularly important.
As structured finance and AI-related investment opportunities expand the available universe, Bariletti believes investors must remain selective about the risks they assume.
“When spreads are tight, sometimes it pays you to play higher up the rating scale,” she says. “This relative value trade will probably strengthen your balance sheet.”
Michela Bariletti will be participating in Longview Networks’ Insurance Investing Roundtable on 14 October 2026.