


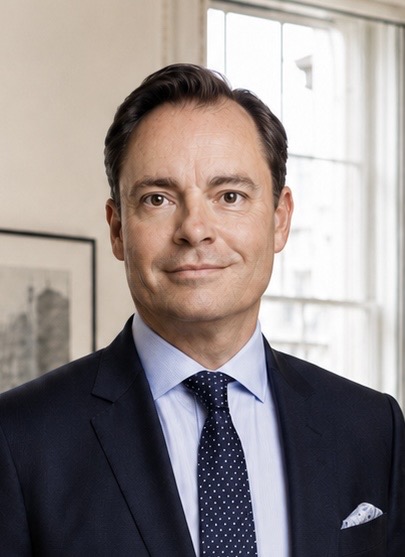
An approaching wave of exits from private equity-backed wealth management platforms will test investor appetite and the sustainability of buy-and-build strategies, according to Dyer Baade & Company chief executive Daniel Baade.
Around one-third of the UK’s 50 private equity-backed wealth management platforms could come to market over the next 12–18 months, creating a significant test of the sector’s ability to deliver returns to investors.
The forecast comes from Daniel Baade, chief executive of M&A adviser Dyer Baade & Company, whose latest research released today shows that private equity-backed buyers accounted for 73.9% of UK wealth management transactions in the first half of 2026.
Baade says a substantial influx of private equity investors around four years ago means many platforms are approaching their anticipated exit dates.
“The interesting question is what will happen to the market,” he says. “Is there enough appetite to buy these firms? And what does it do to prices?”
Consolidation economics
The firm’s research, tracking more than 1,000 transactions since 2015, shows annual deal activity has tripled since 2019–20, reaching 92 transactions in the first half of 2026.
Much of this activity involves smaller financial advice businesses being acquired by established platforms. However, Baade expects competition increasingly to focus on larger businesses capable of materially expanding existing groups or becoming platforms themselves.
The attraction for private equity has been a fragmented market, recurring revenues and predictable demand for retirement advice. Valuation differences have also supported buy-and-build strategies.
The report finds that businesses with up to £500m in client assets trade at a median seven times EBITDA, compared with 13.2 times for those exceeding £2 billion.
“One strategy that PE firms have had for a long time is to buy a bunch of smaller businesses and put them together, as a larger business is more valuable than the smaller ones. There is clear multiple arbitrage,” Baade says.
However, he warns that consolidation alone is no longer sufficient. “We have seen, in the last 12 to 18 months, that some of these PE firms could not exit if they just did that.”
Buyers are becoming more selective, paying greater attention to integration, management quality and adviser retention.
Operational challenge
The report raises questions about the operational benefits of consolidation. Analysis of Financial Conduct Authority data shows the average number of adviser posts per firm increased by 23.7% between 2019 and 2024, while inflation-adjusted revenue per adviser declined by 6.3%.
Although the figures cover the wider advice industry rather than PE-backed firms specifically, Baade believes they highlight weaknesses in integration.
Private Markets and Portfolio Construction – the decisive trends summit | London | 5 November 2026
“When they buy these businesses they would expect some meaningful cost savings,” he says. “But they need to get the balance right between taking some costs out and still delivering exceptional service to clients.”
He argues that losing advisers and their clients can undermine the entire acquisition rationale. “To create value in the sector, you have to do more than just buy small businesses. You must have a clear value creation plan in mind that is based on creating value for clients.”
AI could improve administrative efficiency, although Baade believes its impact will be constrained by the importance of personal relationships in financial advice.
The next owners
Despite concerns about exits, Baade believes demand remains strong, particularly from larger US private equity investors.
He points to the £2.7billion sale of Evelyn Partners to Natwest as evidence that sizeable platforms can attract buyers.
UK wealth management valuations also remain attractive relative to their US counterparts, he says, noting that some British mid-market sponsors have already achieved returns exceeding three times invested capital, with some reported returns as high as six times.
Institutional investment Conferences & Summits from Longview Networks
Baade anticipates further consolidation between PE-backed platforms as investors seek the scale required to attract international capital.
“We will also see further consolidation at the PE-backed side of the market,” he says. “One £10bn under management firm will merge with another £10bn under management firm.”
The next phase could therefore see larger transactions, increasing US ownership and greater scrutiny of operational performance. Private equity owners will need to demonstrate that businesses assembled through acquisitions can deliver sustainable growth and profitability to justify their valuations.