


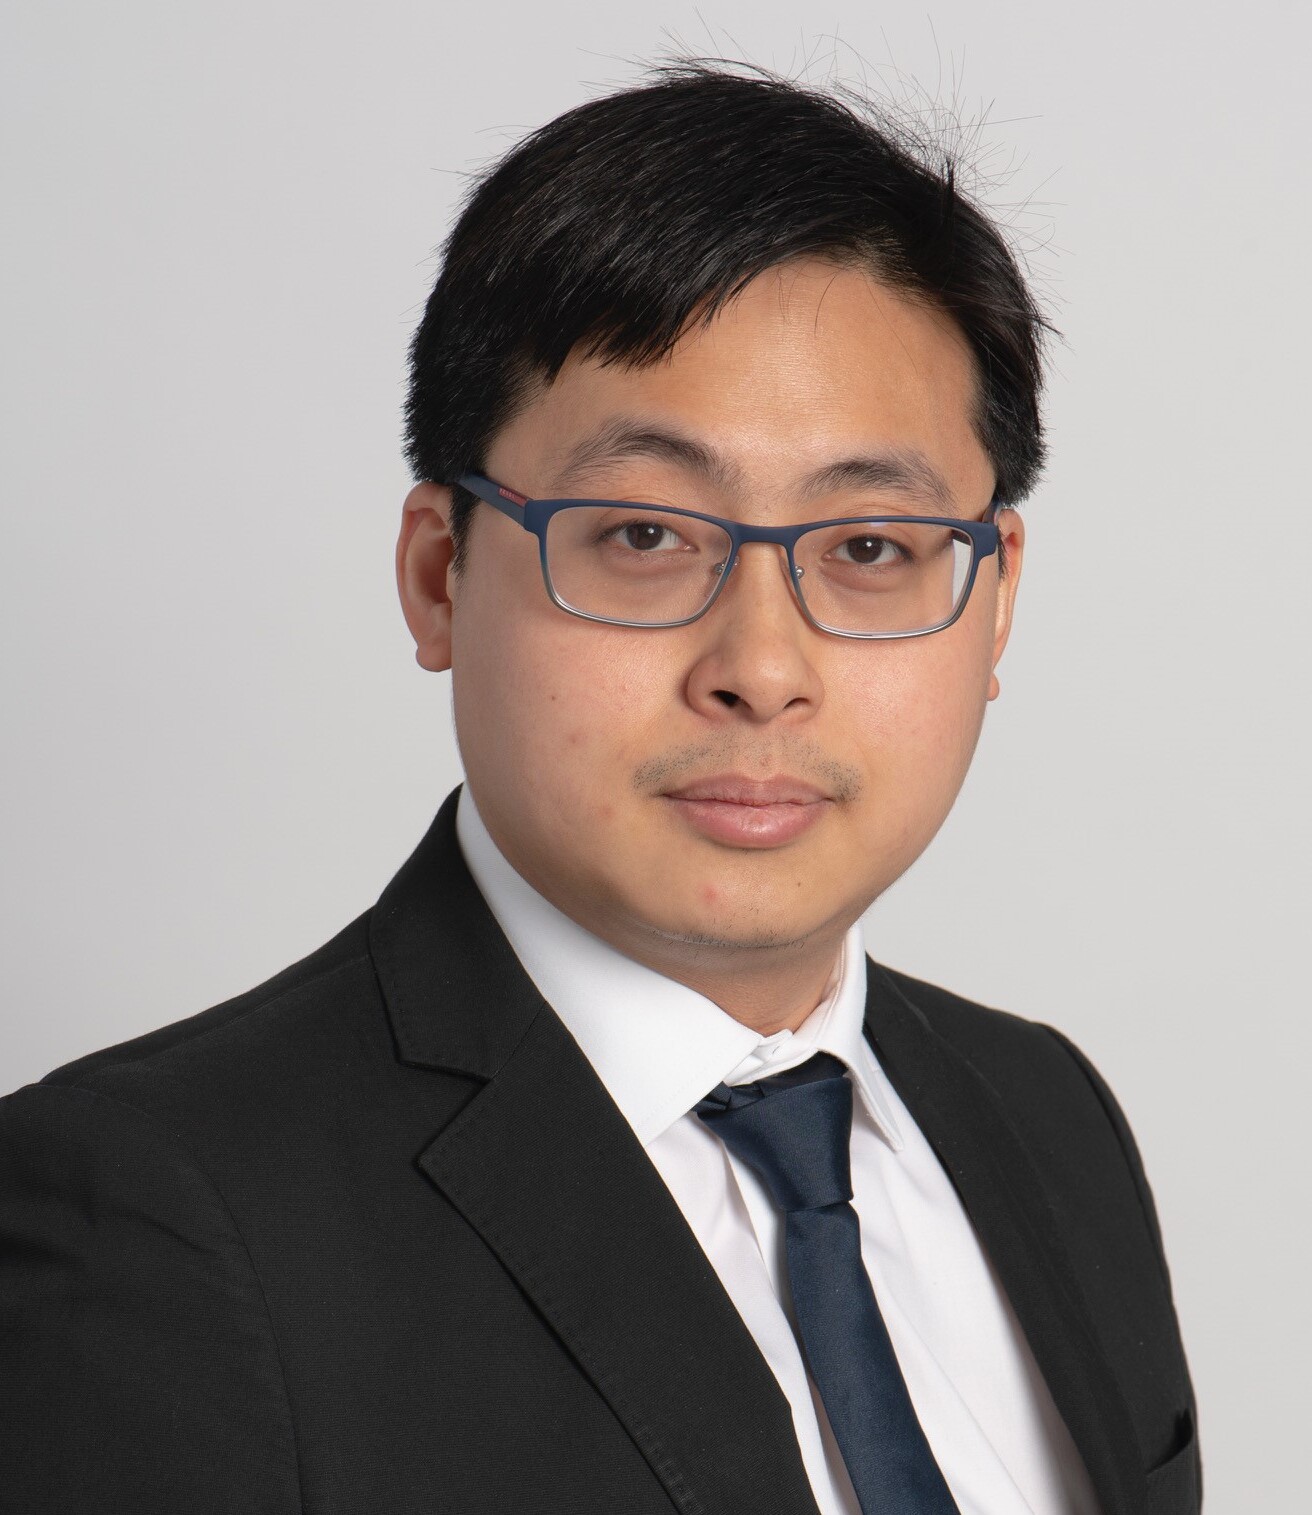
Just Group’s Clarence Er explains how more complex structures and a tougher macro backdrop are redefining how life insurers navigate private credit
UK life insurers are facing a more demanding private credit environment, shaped by regulatory reform, capital constraints and shifting return dynamics.
Just Group head of credit risk Clarence Er discusses how rising scrutiny of structures and ratings is reshaping investment decisions, where innovation is occurring to meet matching adjustment requirements, and why long-dated assets remain attractive despite a challenging macro backdrop.

Speaking ahead of PMP’s Inside the Deal conference, he also shares his views on liquidity premia, NAV-based financing, and the growing complexity facing investors as private credit continues to evolve.
The panel you will be speaking on is called Private Credit 2.0. What distinguishes this market phase from earlier stages of the post-global financial crisis era?
Clarence Er: In the heavily regulated UK life insurance space, there has been far more scrutiny of private markets, both in terms of investment structures and how we can be comfortable with the use of internal ratings. We’ve seen the bar rise quite a bit. Life insurers’ allocations to private markets have been steadily increasing, and it appears that trend will continue.
We then need to find suitable assets to invest in, and private markets serve that purpose extremely well.
Clarence Er
Where has innovation been taking place in the market?
Er: One of the key regulatory requirements for UK life insurers has been the use of the matching adjustment (MA) in our regulatory balance sheet where there are various requirements – such as fixity of cashflows and the ability to hedge back to sterling. A lot of innovation has occurred around structuring assets to make them ‘matching adjustment eligible’, so they are suitable for UK insurers.
The other major driver of our private investments, in our defined benefit pensions business, is our participation in the pension risk transfer market. When we onboard liabilities, the accompanying assets typically come in as cash. We then need to find suitable assets to invest in, and private markets serve that purpose extremely well. Fund managers and brokers are innovating structures that work on our balance sheet – offering the right ratings and returns while remaining regulatorily compliant.
Many US private credit managers have entered the UK market in recent years. What impact has this had?
Er: It has opened up more opportunities. US private credit managers often have access to a broader spectrum of investments than we could traditionally access in the UK. A key challenge for life insurance companies is that our private markets expertise may not be as deep as firms that operate day in, day out across multiple jurisdictions. While international managers can offer new opportunities, they are typically less familiar with UK life insurers’ requirements, so there can be more back and forth to make structures work.
Which areas of private credit offer the most attractive opportunities?
Er: We’re most interested in long-dated assets, such as infrastructure and long income real estate investments. Generally, other investors are less interested in long-dated assets, which means the returns can be quite attractive.
Institutional Investment Conferences & Summits from Longview Networks
Are you mainly focused on the UK in your infrastructure allocation?
Er: We primarily invest in the UK, but we also look internationally. Opportunities in the UK are limited, so we assess international markets as well as newer sectors such as digital infrastructure and data centres. We are always open to evaluating new infrastructure opportunities.
The UK has some big infrastructure plans. Are these filtering through into opportunities?
Er: Yes, but not as much as we would like. Historically, regulations required us to invest only in assets with fixed cash flows. Last year, however, the regulator introduced a new category called ‘highly predictable’ assets, which relaxed that requirement and widened the investable universe. That allows for some uncertainty around cash flows, within limits.
Many infrastructure assets have a construction phase that can last a couple of years before cash flows begin. Previously, we would have had less appetite to consider those assets as they were not an efficient use of our balance sheet. The new allowance makes assets with a construction phase more viable, but only up to a cap of 10% of assets – which is perhaps less than we would like.
UK growth is close to zero and interest rates are heading lower. How do you assess the outlook for private credit?
Er: It has been challenging, due to both lower interest rates and spread tightening. In some cases, we have found that we are better off holding gilts. Under the capital regime, we don’t need to hold capital against gilts, whereas investing in public or private credit requires capital to be held.
Do private credit assets offer better protection in this environment?
Er: Investors generally have more control in private markets, as transactions tend to be bilateral or involve a small pool of investors. We take comfort from having greater ability to intervene and address issues early if performance deteriorates. In public markets, our influence is much more limited. Another advantage of private markets is the ability to negotiate structures that give us additional protection.
Is there still a liquidity premium in private credit relative to public assets?
Er: Yes, but it is harder to capture and you have to work harder for it. I also view the liquidity premium partly as a complexity premium – the more complex the structure, the greater the potential premium.
How do you balance the search for yield with capital preservation?
Er: It’s very challenging. Internally, we set yield and spread hurdles. For any given duration and rating, we need to achieve a minimum yield. If the hurdle is set too high, we won’t transact. If it’s too low, the investment may not be attractive from a balance sheet perspective. We review and update those hurdles as conditions change.
Do you see any risks building up in private credit?
Er: One area of focus is on ratings. We are required to have ratings for all assets, but for many private transactions we rely on internal ratings. With more complex structures, it is harder to predict how a rating will ultimately be assigned. We can make reasonable assumptions, but until a transaction is formally rated, there is always uncertainty. Rating methodologies are not especially prescriptive and don’t cover every structure, so increased complexity inevitably leads to greater ambiguity.
NAV-based financing is growing rapidly. Is this an area you are active in?
Er: NAV-based financing has taken off, but it can be challenging. We haven’t been able to make every structure work within our regulatory framework. We’re seeing far more opportunities, but only a small number have been suitable for us.
What advice would you give investors entering private credit for the first time?
Er: Make use of direct access to borrowers to support your due diligence. Public markets provide a degree of safety in numbers, but in private markets you don’t have that same reassurance. You really need to understand what you’re investing in.
There are often fewer comparables in private markets, which makes it harder to assess relative value. The key challenge is ensuring you are adequately compensated for the risks you’re taking.
Are there still challenges around data and monitoring?
Er: Data itself is generally available for investors that want it. The bigger challenge is the lack of standardisation in monitoring. Different transactions require different metrics, which makes oversight more complex and increases the risk of things being missed. You need a clear understanding of each transaction and what should be monitored.
How do you expect private credit to evolve over the next year or so?
Er: Private markets will continue to play an important role, not just for UK life insurers. While the complexity of structures can be challenging, the rewards can be attractive. There is a lot the industry can do collectively, which is why forums such as Inside the Deal – where investors can share experiences and perspectives – are so valuable.