
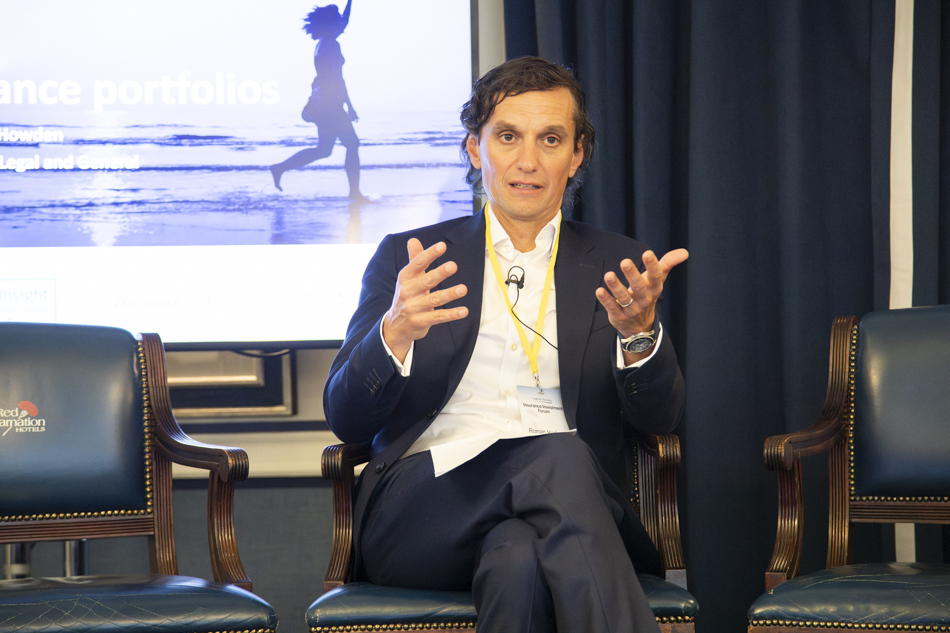

Roman Hederer explains how the UK insurer is adapting its annuity strategy through private markets, productive finance and new sourcing partnerships.
The UK pension risk transfer market continues to grow at pace, bringing fresh capital into insurers’ annuity portfolios and increasing competition for attractive assets. Against that backdrop, insurers are looking beyond traditional corporate bonds to private markets, structured credit and new sourcing partnerships to generate returns and support long-term liabilities.
At Longview Networks’ Insurance Investment Forum, Roman Hederer, head of portfolio management at L&G’s insurance business, discussed how annuity portfolios have evolved, why private credit headlines should be viewed with caution, and how the insurer is approaching asset sourcing, productive finance and regulatory reform.
Bob Tyley, head of insurance investment & ALM, Howden conducted the interview.

How has L&G’s annuity portfolio evolved in recent years?
Roman Hederer: Historically, annuity liabilities were invested predominantly in sovereign bonds. Then portfolios expanded into corporate bonds, and with the introduction of Solvency II there was an increasing focus on private market investments to capture the illiquidity premium that the matching adjustment regime allows insurers to capitalise on.
Up until around five years ago, a typical portfolio – and ours was broadly in line with the market – would have been around 80% credit, both traded and private credit, with around 20% in property and equity release mortgages. Government bonds were a relatively small allocation, mainly held for liquidity management.
A lot has changed over the past five years. Since 2022, rates have risen significantly and swap spreads are higher. Sovereign bonds have become more attractive, not just for liquidity but as a source for spread. At the same time, investment-grade credit spreads are very tight by historical standards.
For insurers, sovereign bonds can be particularly attractive because they require relatively low amounts of capital compared with corporate bonds. That has changed the relative value equation.
We have also seen changes in the equity release mortgage market. It’s still an important asset class in the back book, but in terms of new origination it is probably less of a focus than it was previously.
Higher rates have also given us more flexibility around duration management. Historically, with 12-13 year liabilities, we wanted 12-13 year credit assets. Now, because higher rates reduce duration mathematically and sovereign strategies give us more flexibility, we have a broader opportunity set on the credit side.
Alongside that, the competitive environment has become much more intense, with new market entrants and significant private capital looking to participate both directly and through funded reinsurance structures. As a result, insurers are increasingly focused on back-book optimisation and finding new ways to enhance returns from existing portfolios.
Where do you think L&G has been most innovative in supporting productive finance?
Hederer: Productive finance is a major focus for us, and we are active across infrastructure, housing and a range of other sectors.
A good example of our innovation is our activity in affordable housing. We have committed over £1bn of our capital and are investing alongside third-party capital through our Affordable Housing Fund to help scale delivery across the UK. More recently, we entered into a joint venture with Hyde Group, which brings together annuity capital with Hyde’s national housing platform to develop, manage and operate affordable homes at scale, in a way that is more balance-sheet efficient than traditional approaches.
More broadly, we have continued to evolve how we access sovereign markets and structure portfolios. In addition, reforms have created opportunities in areas such as structured credit, where greater flexibility around duration and solvency treatment allows us to access markets that would have been more difficult for us to invest in a few years ago.
Hear how institutional investors are allocating at PMP’s Private Credit Forum in June.
How do you distinguish between noise and genuine signals in private credit markets?
Hederer: Private credit is often used as a catch-all term, and it means very different things for a UK insurer than it does in much of the press coverage.
Most of the private credit stories in the headlines are focused on US direct lending, typically to middle-market companies with single-B credit ratings. There has been a huge amount of capital flowing into that sector over the past few years and, whenever that happens, you inevitably see some weakening of lending standards.
However, I don’t think that has yet shown up materially in performance because the US economy has been strong. What we’ve seen so far has largely been isolated cases rather than evidence of a broader structural problem.
From a UK annuity insurance perspective, we don’t invest directly in that segment. More than 99% of our portfolio is investment grade. We invest in infrastructure, commercial real estate and corporate private placements. Where we do have indirect exposure is through areas such as CLOs and BDC structures; these are selective and relatively small – our CLO exposure is c.3% of our private credit portfolio, for example.
We monitor the market closely, looking at refinancing risk and underlying credit quality, but we do not believe current exposures are anywhere near a level that would create systemic concerns for either us or the wider insurance industry.
In some cases, negative headlines can actually create opportunities. If there is indiscriminate selling in a sector, and we believe we have the expertise to assess it properly, that can create opportunities to invest at more attractive spreads.
Institutional investment Conferences & Summits from Longview Networks
How important is the firm’s recently announced partnership with Blackstone?
Hederer: Asset sourcing is absolutely critical if you want to remain competitive in the PRT market.
We have a large in-house asset management capability with strong private market expertise in the UK, Europe and the US. Partnering with Blackstone brings additional scale and depth, particularly in the US market.
Through its network and market presence, Blackstone can access large bilateral transactions that we would not otherwise see.
The partnership is really about complementing our existing origination capability. It will remain a smaller component of overall sourcing activity, but it is an important one.
Another factor is flexibility. These partnerships take time to establish, particularly when you are operating within the complexities of the matching adjustment framework and UK regulation. Relative value between asset classes can change quickly, so we wanted a partner with broad capabilities that could help us shift focus between different areas of the market as opportunities evolve.
Have the Solvency UK reforms made a meaningful difference?
Hederer: The reforms have been helpful and have opened up opportunities in areas such as securitised assets, where US insurers have historically had much greater exposure than UK insurers.
In terms of the productive finance agenda, we see opportunity to do more. Areas such as housing and infrastructure are a natural fit for long-term insurer capital, but the combination of investment-grade requirements and the complexity of matching adjustment structures can still limit what we are able to access.
There are many investments that are economically attractive and a good match for long-term insurance liabilities that remain difficult for us to invest in at scale.
We are trying to innovate through structures such as risk sharing or Insurance SRT (the insurance equivalent of the much more established bank Significant Risk Transfer market), and by partnering with third parties that can complement our balance sheet where appropriate.
More broadly, there is an opportunity to unlock further investment if the framework continues to evolve, while maintaining the appropriate prudential safeguards.