
Fiera Capital assesses how a prevailing view that carbon offsetting should only be a tool of last resort and not used in isolation affects fund and asset managers.
The voluntary carbon market worldwide is growing. According to a report from Boston Consulting Group, it reached an estimated $2bn worldwide last year and is set to expand a further fivefold by 2030.
Based on the latest data from Net Zero Tracker, around 130 participants in the UNFCCC Race to Zero – representing $3.9tn in revenue and employing over 10 million people – make use of one form or another of carbon offsetting as part of their emissions targets, including some of the world’s most recognised companies and brands.
That said, companies as diverse as Nestlé, Leon, Gucci, and Shell have withdrawn their support for the use of carbon offsets in recent months. This is in addition to the Carbon Trust withdrawing its own Carbon Neutral labelling scheme. Studies examining the effectiveness of carbon offsets, including one from earlier in 2023, have called into question the reliability and performance of offsets in the wider market. But does this signal the start of a great re-evaluation of carbon offsetting? Yes and no.
Clear Direction
There is a natural concern about the reputational and political risk attached to possible reprisal by financial and marketing regulators such as the FCA, SEC, and CMA to define sustainable investing and take action against misleading environmental claims. Earlier this year, the European Parliament’s position on a proposed Directive on Green Claims included a ban on green targets solely based on offsetting. The mood music is clear: offsetting is not something that should be used in isolation.
This approach is mirrored by high-level standard setting organisations including the COP27 High-Level Expert Group on Net Zero Emissions Commitments of Non-State Entities and the Science Based Targets Initiative, which urge the use of offsets as a means of last resort in decarbonisation, after first seeking to reduce demand and invoke energy efficiency and green energy supplies.
However, we cannot overlook the fact that in the past few years, there has been a move to expand the scope of the emissions that should be attributed to an individual company. A decade ago, and perhaps as recently as two to three years ago, real estate owners and operators typically deemed occupier and construction supply chain emissions to sit outside of their remit.
Yet, investor audiences and standard setters are becoming more demanding of the need to bridge the gap between financial and operational control spheres.
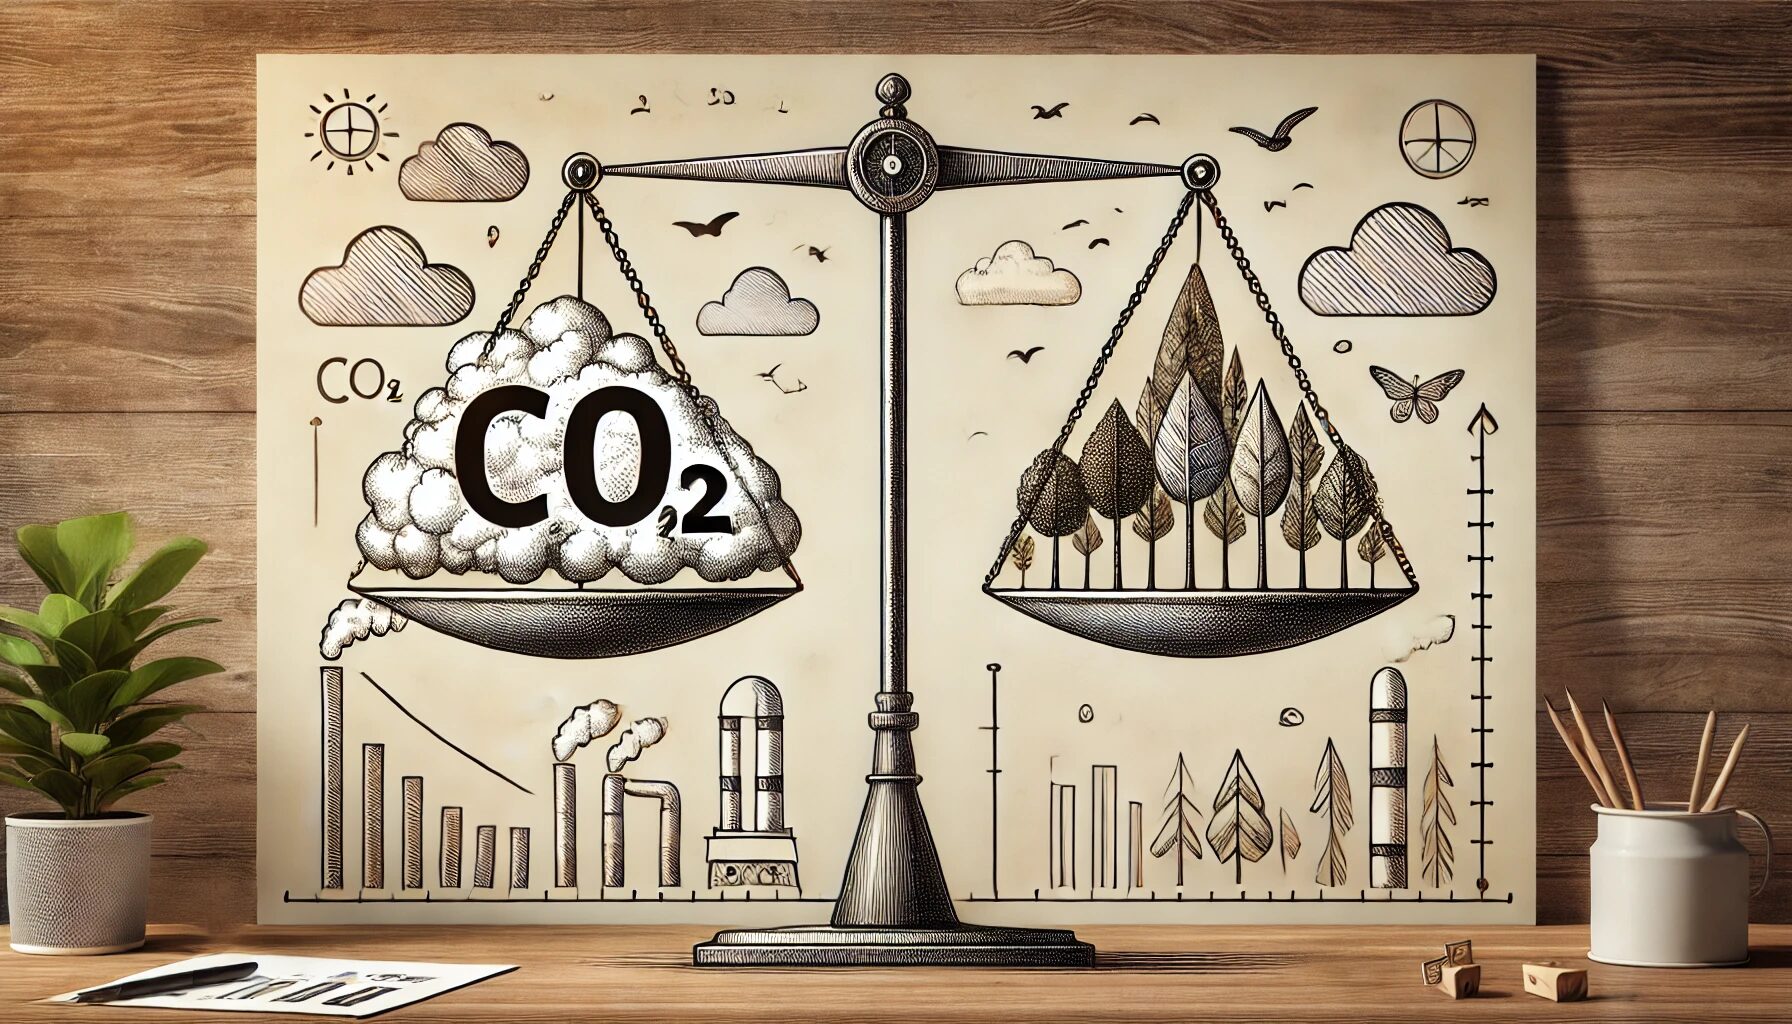
The International Sustainability Standards Board is one of a series of ESG standard-setting bodies that have shifted supply chain emissions to something that should be considered within the emissions boundary of companies. Newer definitions of materiality, including double materiality, are also encouraging a more expansive approach toward emissions reductions. In other words, more carbon is arriving on the balance sheet, risking uncovered emissions without the use of offsets.
Principles-Based Approach
A complementary trend is that many large investors are becoming more demanding of fund and asset managers in terms of having visibility over supply chain emissions, not only in view of decarbonisation but also as a general barometer of an organisation’s ability to handle risk. Having calculated our own pathways to net zero, we find that supply chain emissions from occupiers are hardly residual and represent a chunk of emissions where we are often limited in our ability to intervene. Industry benchmarking clubs like the Better Buildings Partnership have reached similar conclusions, and their recommendations permit offsets as part of a hierarchical approach.
In this context, and pending a fundamental change to the relationship between owners and occupiers, offsets represent a means to address those emissions and also a means to accommodate the uncertainty that comes with the gap between how buildings are forecast to perform and how behaviour subjects those forecasts to a degree of error.
With increased scrutiny from regulators, more demanding investors, and variable quality in the offset market, there is a need for those purchasing and deploying offsets to adopt a principles-based approach. As mentioned, this entails exhausting alternative means to reduce emissions before considering offsets.
To navigate a market where the quality of offsets can vary, the onus is on the purchaser to set their criteria for purchasing offsets. These must include robust criteria for the offsets they will consider with a view to ensuring that accreditation bodies such as the Woodland Carbon Code, which uses science-based methodologies to monitor carbon sequestration, provide confidence in the quality of the premise of an offset. Measurement, reporting, and verification partners afford ongoing monitoring and reporting to ensure that offsets deliver their predicted savings.
